Introduction
Many taxpayers in Pakistan file zero tax returns or declare an annual income below PKR 600,000 to avoid paying income tax. However, many of these individuals simultaneously execute significant financial transactions or acquire high-value assets. The Federal Board of Revenue (FBR) actively tracks financial activities across the country. When a taxpayer’s declared income does not align with their actual financial footprint, the FBR issues official tax notices.
Understanding the legal grounds of these notices is critical for every taxpayer. Official notices issued under Section 114 and Section 111(1) of the Income Tax Ordinance address return non-filing and unexplained income or asset mismatches. This article provides a comprehensive overview of why these notices are issued, how the FBR collects transaction data, the legal implications of receiving them, and the step-by-step procedure to respond through the official portal.
The Risk of Declaring Low Income with High Financial Activity
A common issue among taxpayers is declaring zero income or reporting a salary lower than PKR 600,000 while engaging in large-scale financial transactions or purchasing major assets.
The FBR maintains an extensive tracking system to monitor non-declared wealth and discrepancies. This tracking mechanism relies on multiple data sources, including:
- Computerized Payment Receipts (CPRs)
- Property Registrar Records
- Bank Transaction Logs
When there is a visible conflict between your declared tax status and your actual record of transactions or asset purchases, the FBR uses this tracked data to initiate legal proceedings and issue formal notices.
Understanding Section 114: Notice to File Income Tax Return
Section 114 relates directly to the requirement of filing an income tax return. Under this provision, the FBR can issue a formal notice requiring any individual to submit their return of income.
Key Aspects of Section 114:
- Timeframe Coverage: The FBR can issue a notice under Section 114 for any of the past 5 completed tax years.
- Requirement: If you failed to file your tax return for any year within this five-year window, the FBR retains the authority to demand returns for those specific periods.
- Professional Guidance: Filing tax returns without adequate tax or legal knowledge can lead to errors and subsequent penalties. Taxpayers are advised to engage qualified tax professionals to ensure full legal compliance and avoid future penalties.
Understanding Section 111(1): Unexplained Income, Assets, and Audit Assessment
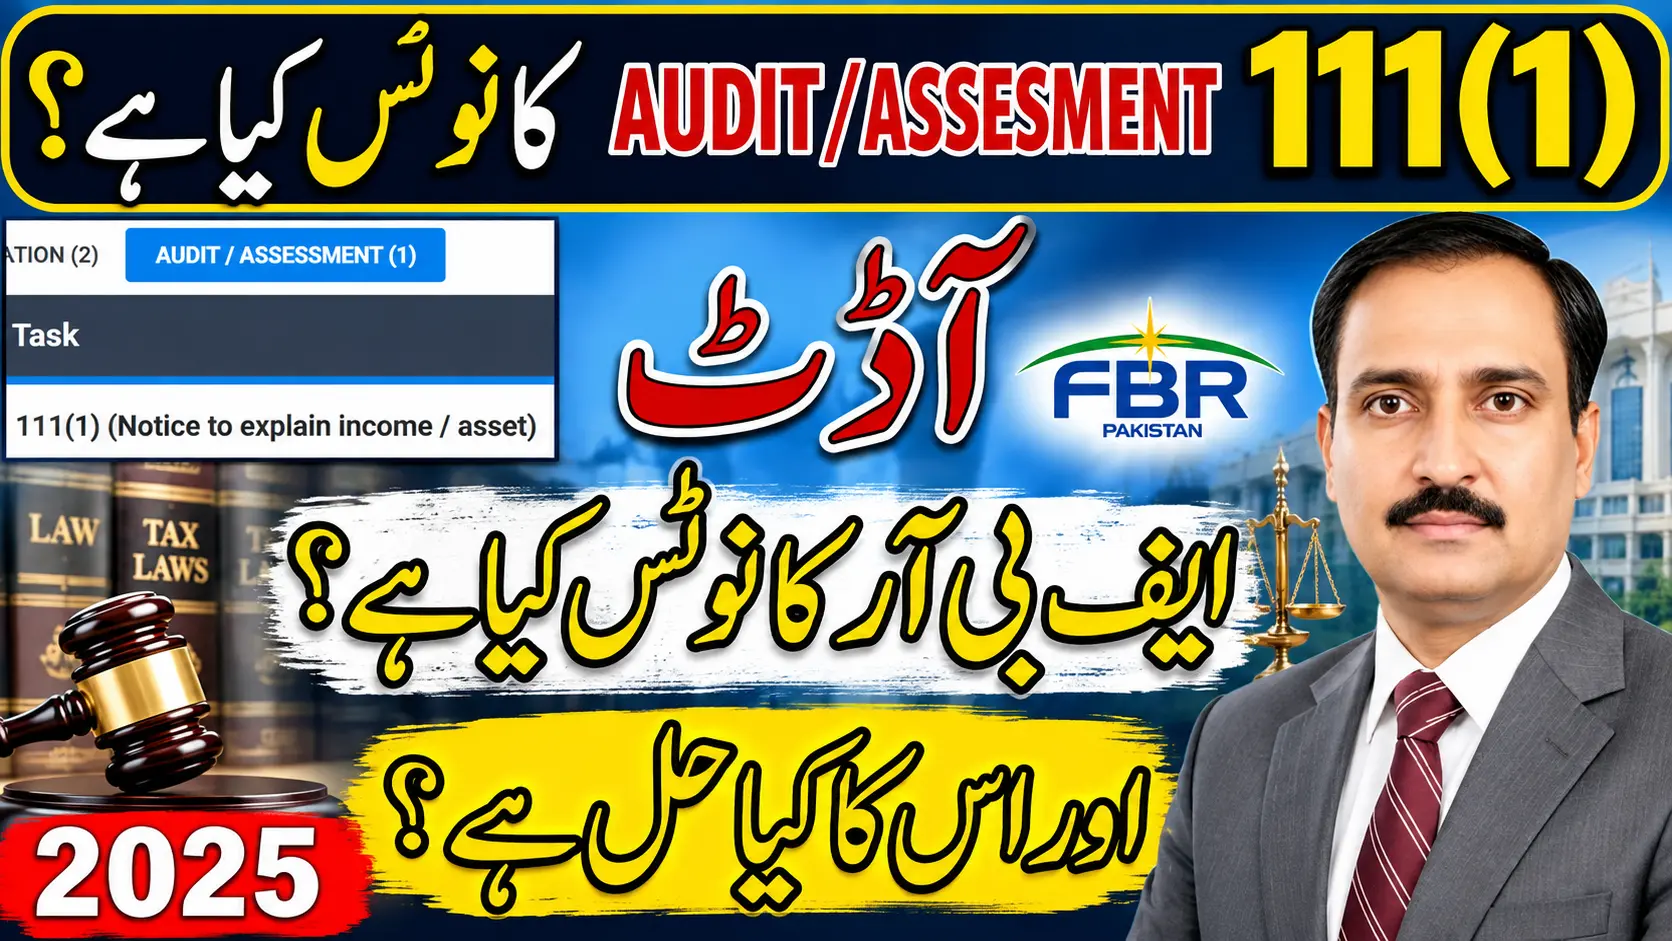
Section 111(1) applies when there is a mismatch between a taxpayer’s declared net assets and their actual financial activities.
Triggers for a Section 111(1) Notice:
A notice under Section 111(1) is issued when discrepancies are identified between your reported figures and actual records regarding:
- Declared net assets versus actual financial transactions
- High-value investments
- Valuable articles owned
- Unexplained expenditures
These discrepancies may be uncovered during an inspection of your account books or flagged through the FBR’s automated data-tracking network.
Concealment of Sales and Receipts
Concealing taxable receipts, production numbers, or sales figures attracts severe tax scrutiny. Attempting to hide actual income or receipts leads to heavy financial penalties and detailed audit assessments by tax authorities.
Step-by-Step Guide: How to Respond to an FBR Notice
If you receive a notice under Section 111(1) or Section 114, you must address it formally within the stipulated deadline
Response Outcomes:
- Satisfaction of Authority: If the FBR finds your written explanation and supporting documentary evidence satisfactory, the matter is resolved at that stage.
- Unsatisfactory Explanation: If the tax authority is not satisfied with the explanation or documents provided, further legal proceedings, audits, or formal hearings will be initiated.
Frequently Asked Questions
Q1: Why did I receive an FBR notice if I filed a zero return?
Answer: You may receive a notice if the FBR’s tracking data (including bank transactions, property registrar records, or CPRs) shows major financial transactions or asset purchases that conflict with your declared zero income or low salary status.
Q2: How many past years can the FBR ask for tax returns under Section 114?
Answer: Under Section 114, the FBR has the legal authority to issue a notice requesting income tax returns for any of the past 5 completed tax years.
Q3: What triggers a notice under Section 111(1)?
Answer: Section 111(1) notices are triggered when there is a mismatch between your declared net assets and your actual transactions, investments, valuable articles, or expenditures discovered in your books or tracked data.
Q4: What happens if someone hides their sales or taxable receipts from the FBR?
Answer: Hiding or concealing sales, production, or taxable receipts leads to severe scrutiny from tax authorities along with heavy financial penalties.
Q5: How should I submit my explanation after receiving an FBR notice?
Answer: You must log into the FBR portal, navigate to the audit/assessment or Section 111(1) notice section, select the explanation option, draft a detailed clarification of your transactions, attach supporting documentary evidence, and submit it before the deadline.
Summary
Filing zero tax returns or declaring income under PKR 600,000 while executing large financial transactions or acquiring valuable assets exposes taxpayers to significant risks. Through CPRs, bank records, and property registrars, the FBR tracks discrepancies between declared wealth and actual spending. Section 114 allows tax authorities to demand returns for any of the last 5 completed tax years, while Section 111(1) targets unexplained assets, investments, and expenditures. To avoid severe scrutiny and heavy penalties, taxpayers must declare their true income and consult experienced tax professionals when responding to notices via the FBR portal before given deadlines.
Call to Action
Stay informed about tax compliance and legal requirements to protect yourself from unnecessary penalties:
- Read Related Articles: Explore our website for more insights on Pakistani legal, tax, SECP, and property matters.
- Subscribe & Follow: Follow our YouTube channel for updates, like, share, and comment with your feedback.
- Ask Your Questions: Leave your queries in the comments section below—we aim to answer them in upcoming content.
- Get Professional Assistance: Contact our expert legal and tax team for professional assistance regarding your tax filings or FBR notices.
Professional Contact Information
Ch. Muhammad Saeed Advocate High Court Senior Member, High Court Bar Association Lahore
We are an association comprising Lawyers, Chartered Accountants, Computer Engineers, and AI Experts providing professional services in:
- Property Disputes & Legal Matters
- Income Tax & Sales Tax
- Company Registration & SECP Matters
- NTN Registration & FBR Matters
- Refund Claims
Contact Information:
- Phone: 0341-1259762
- Email: msaeedadv86@gmail.com
Sponsors interested in promoting their products or services are also welcome to reach out via the provided contact details.