Learn the truth behind viral tax claims for digital creators in Pakistan, including view-based tax myths, withholding tax, and PSEB registration.
Pakistani digital creators tax, YouTube income tax Pakistan, Rs 195 per 1000 views myth, withholding tax digital creators, PSEB 0.25 percent tax rate, FBR online earning tax, classification of income FBR, tax documentation content creators Pakistan, FBR tax liability creators, Chaudhry Muhammad Saeed Advocate
As digital content creation transitions from a casual hobby into a full-time profession, social media creators, YouTubers, TikTokers, and Instagrammers in Pakistan face growing questions regarding their tax obligations. Earning income online through monetization, brand sponsorships, paid promotions, or digital services brings creators within the scope of Federal Board of Revenue (FBR) tax regulations. Understanding these legal realities is crucial to managing online earnings effectively and avoiding common misconceptions circulated on social media. This comprehensive guide clarifies viral claims regarding view-based taxes, details how income is classified, explains withholding taxes, and outlines the role of PSEB registration for tax compliance.
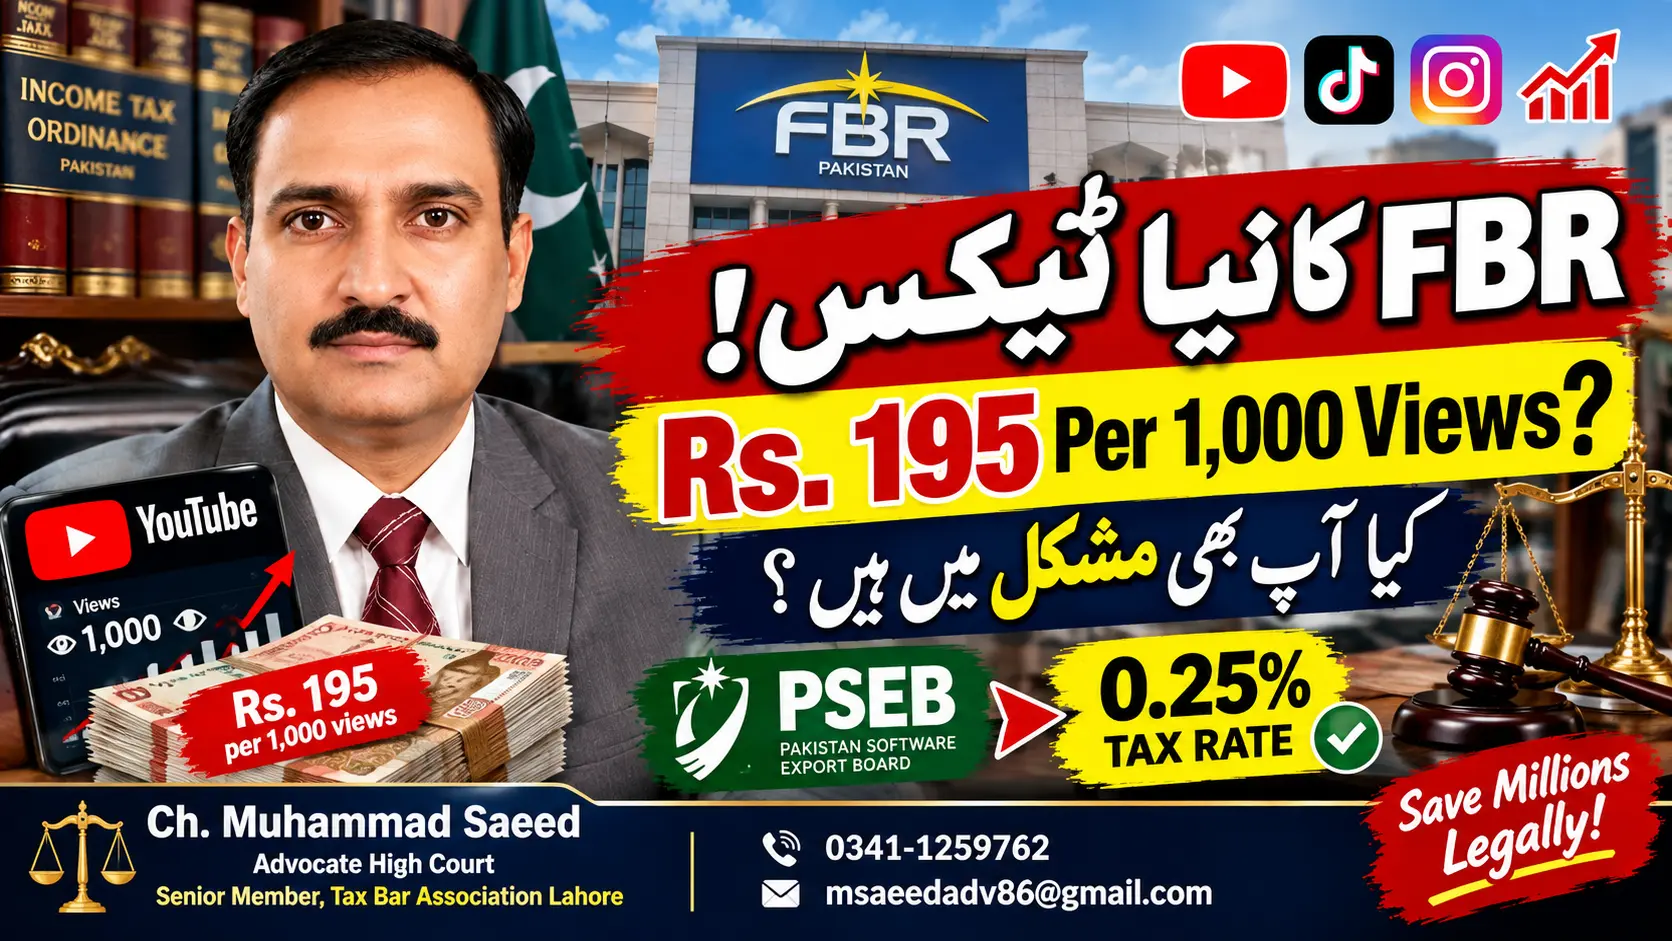
The Truth Behind the Viral “Rs 195 per 1,000 Views” Claim
A figure widely discussed across social media platforms suggests that creators must pay a fixed tax of Rs 195 per 1,000 video views. For instance, some claims suggest that a video accumulating 100,000 views incurs a mandatory tax liability of Rs 19,500. However, this conclusion is legally incorrect.
- Benchmark vs. Fixed Tax: The Rs 195 figure serves merely as a benchmark to explain reported remuneration or income estimates. It is not an automatic, fixed tax applied to view counts.
- Views Do Not Equal Income: Consider two creators who each receive 1,000 views on a video. One creator earns money through platform monetization, while the second receives no payment. Assuming both have the same income based solely on view counts is inaccurate.
Tax obligations are not determined by view counts alone, but by applicable legal rules, actual earnings, and available supporting evidence.
Classification of Income and Sources of Revenue
Modern digital creators generate income from multiple channels, including YouTube monetization, Pakistani brand sponsorships, paid promotions, and various digital services. In tax law, every payment is not treated identically.
Why Source Matters
For example, if Ayesha receives a payout directly from YouTube, while Ali receives payment from a local Pakistani brand for a sponsored video, their income sources differ significantly. Because the revenue sources are distinct, the applicable tax treatments, documentation requirements, and legal provisions also differ.
The Principle of “Classification of Income”
Before applying any tax provision or calculating liability, the tax authority must first determine the precise legal nature and category of the income. Once the income is properly classified under the relevant law, the corresponding tax rules are applied. Relying on generic social media headlines as final legal advice can lead to incorrect conclusions.
Tax Deductions, Withholding Tax, and Proper Documentation
While legal mechanisms exist to ensure creators claim the correct tax treatment under applicable laws, no single shortcut applies universally to every creator.
Understanding Key Tax Terms
- Withholding Tax: If a 5% withholding tax rule applies to a specific transaction, the tax is deducted at the time of payment. For example, a 5% withholding deduction on a gross amount of Rs 1,000,000 equals Rs 5,000. However, a 5% deduction does not apply automatically to every payment received by every creator.
- Deemed Revenue: In certain scenarios, tax regulations may use a prescribed basis or benchmark to estimate income. However, benchmarking must be properly understood and not confused with actual cash received or final tax liability.
- Documentation: Maintaining accurate financial records is essential for explaining tax positions if the FBR issues a notice or inquiry.
Essential Records to Maintain
Creators receiving payments through bank channels should keep comprehensive records, including:
- Bank credit statements
- Platform earning statements
- Contracts and invoices
- Records of relevant business expenses
Deductions vs. Final Settlement
If a bank deducts withholding tax on an incoming payment, creators must verify whether that deduction qualifies as an adjustable tax, a final tax, or falls under a specific tax provision. A bank withholding tax deduction does not automatically mean your total tax liability is fully settled.
PSEB Registration and the 0.25% Tax Rate Claim
A common belief among content creators is that registering with the Pakistan Software Export Board (PSEB) automatically subjects all their earnings to a reduced 0.25% tax rate.
- Not a Universal Rule: Eligibility for specific export-related reduced tax regimes depends on meeting strict statutory conditions, the legal nature of the income, proper registration, and current tax laws.
- Foreign Payments: Receiving payments from foreign platforms does not, on its own, prove that the income qualifies for the reduced 0.25% rate regime. Income classification and specific statutory criteria must be verified first.
- Recommendation: Pakistani digital creators are advised to register with the PSEB to explore the potential 0.25% tax advantage on qualifying export income, provided they verify and comply with all underlying requirements of the relevant tax rules.
For official and binding legal information, creators should always consult the Finance Act and relevant Statutory Regulatory Orders (SROs) on the official FBR website rather than relying on social media posts.
Frequently Asked Questions
Question: Is there a fixed tax of Rs 195 for every 1,000 views on social media videos?
Answer: No. The Rs 195 figure is only a benchmark used to explain reported remuneration or income estimates. Tax liability is based on actual earnings, applicable legal rules, and evidence—not automatically on video view counts.
Question: Do all content creators pay the same tax rate on their online income?
Answer: No. Tax treatment depends on the classification of income, the source of payment (such as foreign platform monetization versus local Pakistani brand sponsorships), and the relevant legal provisions that apply to each specific revenue type.
Question: Does bank withholding tax cover my total tax liability automatically?
Answer: Not necessarily. A withholding tax deduction by a bank must be checked to determine whether it is an adjustable tax, a final tax, or treated under a specific provision. Tax deducted at the bank level does not inherently mean your overall tax liability is completely settled.
Question: Does PSEB registration automatically guarantee a 0.25% tax rate on all earnings?
Answer: No. While PSEB registration offers an avenue to claim a 0.25% tax rate on qualifying export income, it is not a universal rule. Creators must satisfy specific conditions, income categories, and current legal requirements to qualify.
Question: What records should digital creators keep for FBR compliance?
Answer: Creators should maintain detailed records including bank payment receipts, platform earning statements, contracts, invoices, and records of relevant expenses to substantiate their financial position in the event of an FBR inquiry.
Conclusion
Understanding FBR tax compliance requires digital creators in Pakistan to separate online viral claims from legal realities. Video views alone do not determine tax obligations, and different sources of income—such as platform earnings and local brand sponsorships—carry distinct tax treatments and documentation requirements. While withholding tax may be deducted at the bank level, proper documentation of income statements, invoices, and expenses remains vital. Furthermore, while registering with the PSEB offers a potential tax rate advantage of 0.25% on export revenue, creators must fulfill specific legal conditions to qualify. Official guidance should always be verified through the Finance Act and relevant SROs on the FBR website.
Professional Consultation and Contact Information
For official advice and legal representation on tax, corporate, and property matters, you can connect with qualified legal and financial professionals.
Chaudhry Muhammad Saeed, Advocate High Court Senior Member, High Court Bar Association Lahore
Our association includes Lawyers, Chartered Accountants, Computer Engineers, and AI Experts providing professional services in:
- Property Disputes and Legal Matters
- Income Tax and Sales Tax
- Company and NTN Registration
- Refund Claims
- SECP and FBR Regulatory Matters
Contact Details:
- Phone: 0341-1259762
- Email: msaeedadv86@gmail.com
- Sponsorships: Brands and sponsors interested in promoting products or services are welcome to reach out.
If you found this article informative, please share your thoughts or questions in the comments section below, share this post with fellow creators, and stay tuned for further legal and tax guidance.